Pagina 1 van 3
Produce Investments PLC
Geplaatst: 2 november 2017, 23:28
door Umi
Er was hierover al een kort onderhoud in het 'Total Produce-topic'. zie hieronder
total-produce-t18239-150.html
Produce Investments "Grows, sources, packs and markets fresh potatoes, daffodil flowers and bulbs"
verdere introductie is niet nodig, daarvoor hebben ze een 'factsheet'
https://www.produceinvestments.co.uk/me ... b-2017.pdf
MarktCap = £ 51M
Net Debt = £ 28M
avg. 5y FCF (excl. WC)= £ 7,5M (CapEx voor 2017 excl. de £ 6,1M voor packing facility)
omdat we conservatief zijn, een FCF van 7M.
fair value = +- £ 85M (multiple van 15, min +-20M aan schulden eind dit jaar)
opwaarts potentieel = 66%
Pro:
- vrij stabiele cashflows + marges
- noodzakelijke producten (over narcissen valt natuurlijk te discussiëren)
- schulden onder controle
- efficiëntieverbeteringen recent doorgevoerd
- stevig & groeiend dividend
- FCF yield van 13,7%!!
- streven naar verdere diversificatie
- geografische spreiding in hun activiteiten binnen de UK.
- enkele groot-aandeelhouders waaronder insiders
https://www.produceinvestments.co.uk/me ... 201016.pdf
contra
- het werkkapitaal zit al 10 jaar tegen? (vergt meer onderzoek)
- Microcap + lage liquiditeit & soms moeilijk verhandelbaar
- Geen groeier (mss wel qua volumes?)
- Brexit (wat met goedkope Oost-Europese werkkrachten?)
- 'Chairman' stopt eind deze maand & heeft na resultaten al zijn aandelen van de hand gedaan.
- zo goed als volledige omzet in UK
ps Dank aan Poldermol & Jens om dit te belichten.
oh... & dit is GEEN koopadvies!
Re: Produce Investments PLC
Geplaatst: 11 november 2017, 17:18
door Umi
Koers is ondertussen gezakt tot onder niveau van voor de (goede) jaarresultaten. (beste halfjaarresultaten ooit dacht ik, na slecht H1)
ivm werkkapitaal; stijging had vooral te maken met de hoge aardappelprijzen & lange termijncontracten. De nieuwe oogst zou bovengemiddeld zijn, gevolg is lagere aardappelprijzen (is gunstig als ik het goed begrijp) & dan zou het werkkapitaal moeten meezitten in dit boekjaar.
https://potatoes.ahdb.org.uk/news/nepg- ... on-upwards
http://www.londonstockexchange.com/exch ... ml?lang=en
laats verhandelde koers; 1,775
markcap = € 47,8
opwaarts potentieel aan deze koers al 78% volgens mij.
edit; FCF Yield van 14,6%
& dan lees ik ergens dat goedkope aandelen niet meer bestaan

Re: Produce Investments PLC
Geplaatst: 12 november 2017, 22:52
door Umi
Re: Produce Investments PLC
Geplaatst: 4 december 2017, 23:27
door Umi
Nog iets ivm het aandeelhouderschap van PIL...
Jerry Zucker Revocable Trust bezit dus +- 26% op heden. Nu las ik overlaatst ergens dat die in het verleden een belang van 13% in Fyffes hadden & we weten wat daarmee gebeurd is

Re: Produce Investments PLC
Geplaatst: 4 december 2017, 23:33
door Umi
Umi schreef: ↑9 oktober 2017, 01:08
Poldermol schreef: ↑5 oktober 2017, 23:22
En wat de schulden betreft, dit jaar gaan ze ook de site van een gesloten fabriek verkopen. Dus ik reken erop dat de YE net debt uitkomt op 21-22M GBP uitkomt, wat 1.5X EBITDA is.
jup, had ik gelezen in het jaarraport. Enig idee wat die gaat opbrengen?
Ik had ruwweg geschat op een net debt van 20M.
Poldermol schreef: ↑9 oktober 2017, 08:57
Geen idee, ze hebben de site wel gestript, maar ik weet niet of ook de gebouwen afgebroken werden en er dus een 'clean' stuk grond verkocht wordt... Dus ik kijk het even aan om te zien wat er effectief van komt...
Was nog eens het jaarverslag aan het doornemen & viel me op dat bij de balance sheet volgende stond;
Assets held for sale 1,250
Staat sinds 2016 op de balans & in 2017 nog steeds. Dus ik gok dat die 'gesloten fabriek' nog voor dat bedrag in de boeken staat. Daarom nog niet het bedrag wat ze ervoor willen krijgen.
Re: Produce Investments PLC
Geplaatst: 4 december 2017, 23:41
door Umi
ff een post ivm werkkapitaal hier plaatsen..
Poldermol schreef: ↑5 oktober 2017, 23:18
Ik legde het zo uit aan mijn lezertjens:
Should you be worried about the continuous need for working capital investments?
A large part of the operating cash flow was invested in the working capital position. Whilst 1.5M GBP was explained by Produce Investments paying some of the outstanding invoices, the total amount of receivables and inventory levels increased as well.
This isn't necessarily bad. As you might remember, PIL delivers their products to retail chains and those don’t really pay ‘on the spot’. So as the revenue increases, the total amount of outstanding invoices will increase as well. In fact, the increase of the receivables wasn’t exorbitantly high, as you can see in the next image.
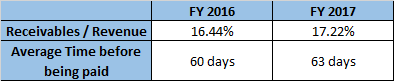
So, yes, PIL has to wait a little bit longer to see their invoices being paid, but the difference isn’t very alarming at all. On top of that, it’s able to benefit from an ‘invoice finance’ facility (which probably is a straightforward ‘factoring’ agreement.
The higher investment in the inventory and biological assets level is actually justified (and very reasonable as well). Let’s compare the 2017 results with 2016.
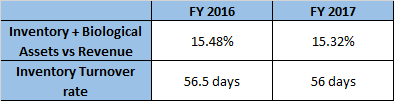
So, the inventory turnover rate has actually decreased, although you have to take a certain seasonality effect into consideration as well. Produce Investments usually ends the year with relatively low inventory levels.
Ook nog ff toevoegen dat werkkapitaal vooral steeg door hogere gronstofprijzen (ook reden van sterke stijging in revenue dus), in combinatie met de (nieuwe) langere termijncontracten (3jaar).
Re: Produce Investments PLC
Geplaatst: 5 december 2017, 10:09
door Lilly
Van die SEAQ begrijpt de deze ook niet veel hoor. Er ligt al weken een order in de markt om een aantal aandelen aan te kopen tegen 172,5. Dat order wordt niet uitgevoerd, terwijl andere orders wel uitgevoerd worden aan een lagere prijs.
Vandaag ben ik het beu en leg ik mijn limiet op 175. Wat denk je? Order uitgevoerd aan 170,5.

Ge hoort mij niet klagen, maar daar versta ik nu de botten van...

Re: Produce Investments PLC
Geplaatst: 5 december 2017, 10:21
door jens_dev
Ja, dat is bij Norcros ook. Er kan buiten het orderboekje om worden gehandeld, aan prijzen die totaal losstaan van dat orderboekje.
https://www.ft.com/content/13e183ee-c09 ... a6e068f464
Zouden ze hier last van hebben? Ze zeiden al eerder dat dit voor hen het grootste risico van Brexit was.
Re: Produce Investments PLC
Geplaatst: 5 december 2017, 23:46
door Umi
jens_dev schreef: ↑5 december 2017, 10:21
Ja, dat is bij Norcros ook. Er kan buiten het orderboekje om worden gehandeld, aan prijzen die totaal losstaan van dat orderboekje.
https://www.ft.com/content/13e183ee-c09 ... a6e068f464
Zouden ze hier last van hebben? Ze zeiden al eerder dat dit voor hen het grootste risico van Brexit was.
Mogelijks.
Voor 'soft fruit' is iig meer handenarbeid nodig, dus ik gok dat die sector het zwaarder zal hebben.
Ik ga er ook wel vanuit dat de regering er wel voor zal zorgen dat dit probleem opgelost zal worden...
Het is dat, ofwel hogere voedselprijzen & hoge inflatie

de aardappelen zijn iig al gerooid
https://potatoes.ahdb.org.uk/publicatio ... ember-2017
4 December 2017
GB 2017 Production up 15% to 6.04 Million tonnes
AHDB Potatoes’ first provisional estimate of total production in Great Britain for the 2017 crop is up 15% on the year at 6.04Mt, the highest level since 2011. The early 2017 area estimate of 120,897ha has been revised up to 122,779ha, now based on 98% of planting returns received, compared with 60% for the earlier estimate. The estimated average net yield for 2017 is 49.3t/ha
The finalised production figure for 2016 is now 5.24Mt, compared to the original estimate of 5.22Mt. This increase is based on a 0.5% revision of the area estimate for 2016 from 116,225ha to 116,827ha. The estimated average net yield for 2016 was 45t/ha.
Packing trade in England remained unchanged from last week for most, with free-buy tonnage remaining steady.
Scottish packing trade remained steady, although it has been a struggle for some to secure buyers. The national abundance of potatoes and limited storage is reportedly forcing supplies onto the market.
Many in the bag market are hoping for a festive boost.
Re: Produce Investments PLC
Geplaatst: 6 december 2017, 08:45
door jens_dev
Maar die Britse regering is ontstellend zwak. Inflatie ligt er nu al boven de 3%. Food inflation boven de 4%. En de lonen voor Europese labour zullen in £ ook wel een stuk duurder zijn nu, terwijl produce bedrijven sowieso slechts een zeer lage marge hebben.
Re: Produce Investments PLC
Geplaatst: 6 december 2017, 23:34
door Umi
jens_dev schreef: ↑6 december 2017, 08:45
Maar die Britse regering is ontstellend zwak. Inflatie ligt er nu al boven de 3%. Food inflation boven de 4%. En de lonen voor Europese labour zullen in £ ook wel een stuk duurder zijn nu, terwijl produce bedrijven sowieso slechts een zeer lage marge hebben.
Klopt.
Maar de pond stond tijdens boekjaar 2017 al zwak & ook toen draaiden ze behoorlijke cashflows. Daarnaast beweren ze (voorlopig) genoeg seizoensarbeiders te kunnen overhalen. & is dit enkel van toepassing in hun afdelingen in Jersey & Rowe...
To date the Group has no issues as we have a high retention and return rate in our two seasonal businesses of Jersey and Rowe Farming. We have a long-standing policy of recruiting directly, offering good terms and favourable working conditions.
80a90% van hun verpakte aardappelen kweken ze niet zelf. Daarnaast zal een stijgende kost uiteindelijk doorgerekend worden aan de eindklant. Import uit Eurozone zal ook duurder zijn vanwege wisselkoers.
Grootste deel van hun winsten lijkt me uit hun packaging-afdeling te komen, als ik hun business tegoei begrijp tenminste...
De VKS-marges zijn niet hoog nee (3,3 à 4,9% de laatste 5jaar), maar wel een stuk hoger als die van Total Produce bvb.
Re: Produce Investments PLC
Geplaatst: 6 december 2017, 23:50
door Umi
Daarnaast is men nog hoopvol over 2 kleinere afdelingen;
Swancote Foods
Since the contamination incident at Swancote Foods in May 2015 and the disruption to that business, the Directors continue to carefully monitor the Swancote recovery plan. The key issue for this facility is securing additional volume to take the facility back to and beyond the production volumes achieved prior to the contamination issue. The Directors continue to believe that this remains achievable.
Comments relative to the key assumptions used in the value in use calculation are as follows:
– 2018 forecast EBIT of £470,000 is based on the latest forecasts prepared. This is higher than in the past two years, when Swancote has
been loss-making. The Directors are confident that this improved EBIT will be achieved due to a new customer that is expected to deliver a further 5,000T of processing and thus increase overall production to approximately 18,000T. At the date of approval of the annual report, the contract with this new customer is not yet signed but the Directors confirm that they expected this to be finalised during the remainder of 2017.
– EBIT growth of 10% from 2019 through to 2022 is expected to result from increased production volumes, primarily to existing customers, through broader product offering.
Synergies
The Fresh business has benefited from the original Swancote acquisition through access to original Swancote customers and the processing of outsized potatoes. The revenue and savings from this original acquisition continue to be enjoyed by the Fresh business. The key assumptions, in the value in use calculation, reflect past experience and remain consistent with those used in previous periods.
Rowe Farming Limited
Rowe Farming Limited’s business has enjoyed significant growth of its capacity, sales volumes and asset base over the past three years against a backdrop of stagnant sales prices and margins in a number of markets. The Directors and management have reviewed the customer base and sales strategies on a customer by customer basis and identified a number of areas of development for the business in the short and medium term.
Comments relative to the key assumptions used in the value in use calculation are as follows:
– 2018 forecast EBIT of £1.93m is based on the latest forecasts prepared and is significantly higher than the EBIT achieved in 2017.
However, this level of EBIT is at a level consistent and also below other years since acquisition. The Directors are confident that the increase in EBIT will be achieved through achievable increases in price, through pursuing new retail customers, and also due to adverse trading issues experienced in 2017 not being expected to recur.
– EBIT growth of 5% from 2019 through to 2022 is expected to be driven through increasing sales penetration into retail, and a shift away from wholesale.
Re: Produce Investments PLC
Geplaatst: 2 februari 2018, 00:35
door Umi
De voorzitter Barrie Clapham vergroot zijn positie met een zeer klein pakket van +- £ 8000. (de man bezit 22% ofzo)
Re: Produce Investments PLC
Geplaatst: 2 februari 2018, 10:38
door Joost1000
Umi schreef: ↑2 februari 2018, 00:35
De voorzitter Barrie Clapham vergroot zijn positie met een zeer klein pakket van +- £ 8000. (de man bezit 22% ofzo)
Gewoon meedoen met hem, ik heb onlangs ook wat gekocht.
Re: Produce Investments PLC
Geplaatst: 2 februari 2018, 15:29
door Umi
Joost1000 schreef: ↑2 februari 2018, 10:38
Umi schreef: ↑2 februari 2018, 00:35
De voorzitter Barrie Clapham vergroot zijn positie met een zeer klein pakket van +- £ 8000. (de man bezit 22% ofzo)
Gewoon meedoen met hem, ik heb onlangs ook wat gekocht.
Ik heb al een positie van rond de 6%. Dat is voorlopig voldoende voor een small/micro cap. Als de resultaten/outlook goed blijken kan het zijn dat ik bijkoop.